Telia Lietuva 2026 Q3 financial review
Profits up, but not free cash flow
Telia Lietuva maintained solid operating momentum and earnings growth in Q3 2026, although higher capital investments weighed on free cash flow.
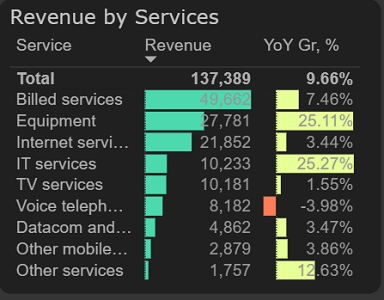
Revenue grew slightly faster than in the first half of the year, rising 9.7% YoY (+€12M) in Q3. The key growth drivers remained unchanged: IT services revenue increased by 25% YoY (+€2M), equipment sales revenue by 25% YoY (+€5.6M), and billed services revenue by 7% YoY (+€3.4M).
Revenue by services, 2026 Q3
In Q3, the operating profit margin increased by another 1 percentage point compared to the same period last year, while the EBITDA margin remained broadly stable. Profitability was supported by a 7.6% YoY reduction in employee costs. On the other hand, the cost of goods and services and other operating expenses grew faster than revenue, increasing by 14% YoY and 19.5% YoY, respectively.
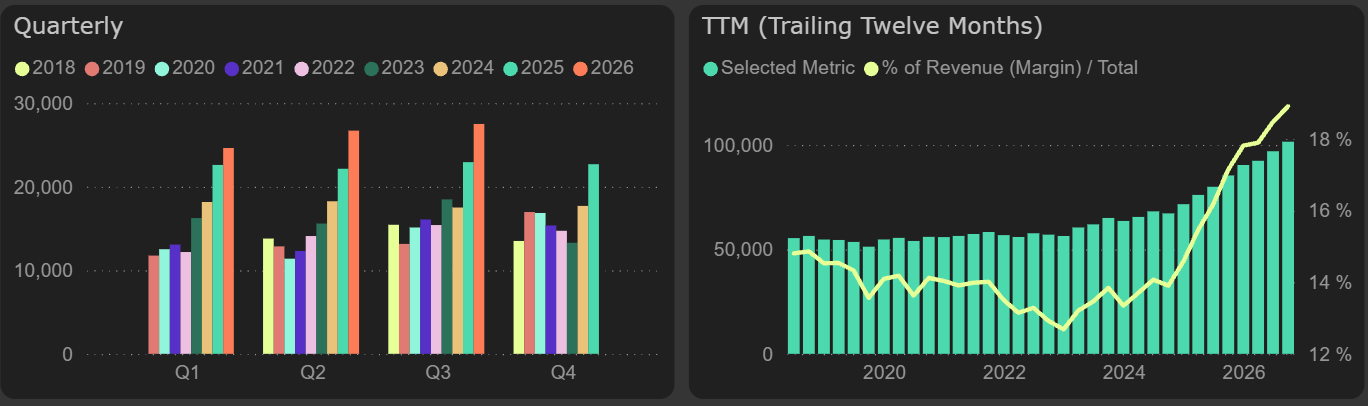
The company's net profit increased by 20% YoY to €27.5M in Q3. Over the first nine months of the year, net profit rose 16% YoY to €78.8M.
Net profit
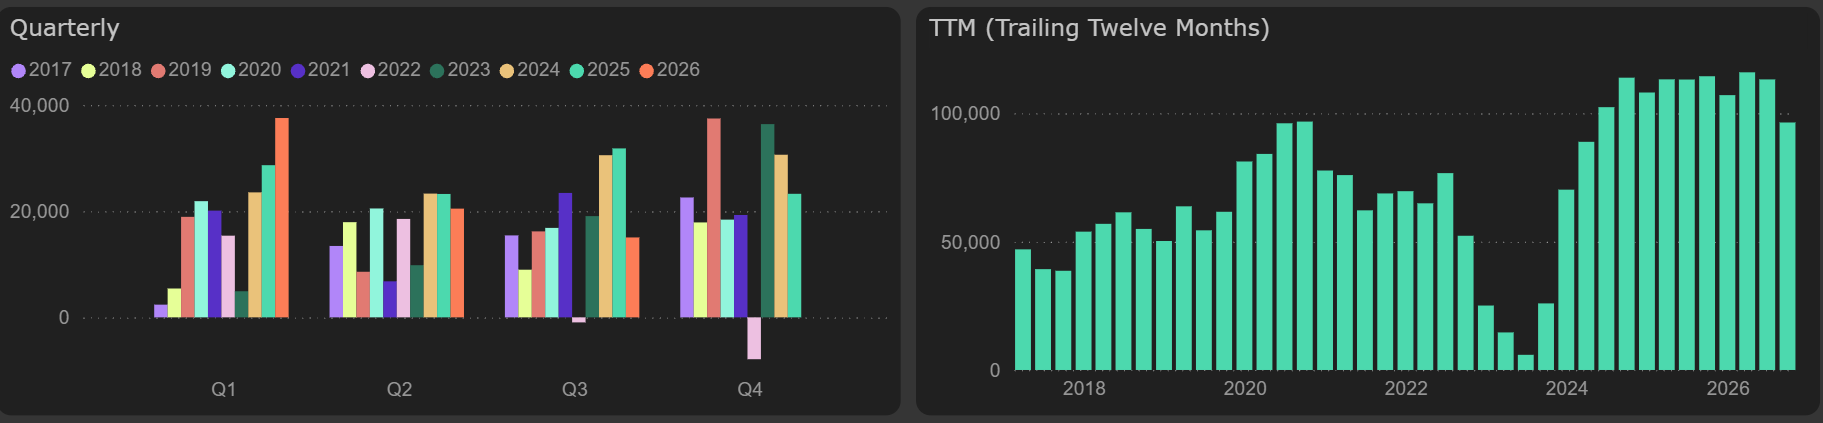
Trailing 12-month free cash flow declined to €96.4M, with the FCF yield falling to 7%. Although funds from operations continued to grow by 7% YoY in Q3, a doubling of capital expenditures weighed on free cash flow. Over the first nine months of the year, capital expenditures reached €66M, up 45% YoY.
Free cash flow
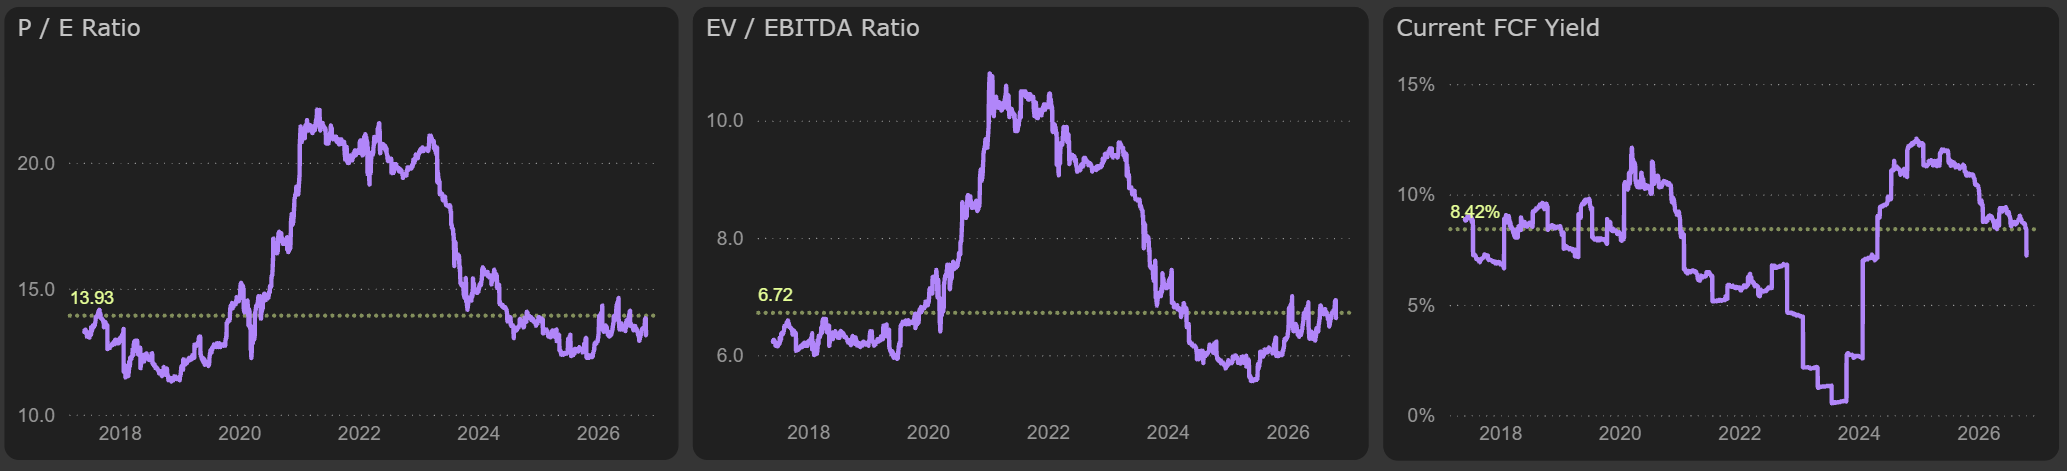
Valuation multiples remained relatively stable, with the P/E ratio at 13.1x and EV/EBITDA at 6.6x.
Valuation multiples


Artea Bank | 2026 Q3 | Net interest income is growing, but where are the profits?
Artea Banks Q3 results tell a very different story from its Estonian peers, LHV Group and Coop Pank, both of which reported growing ...

